
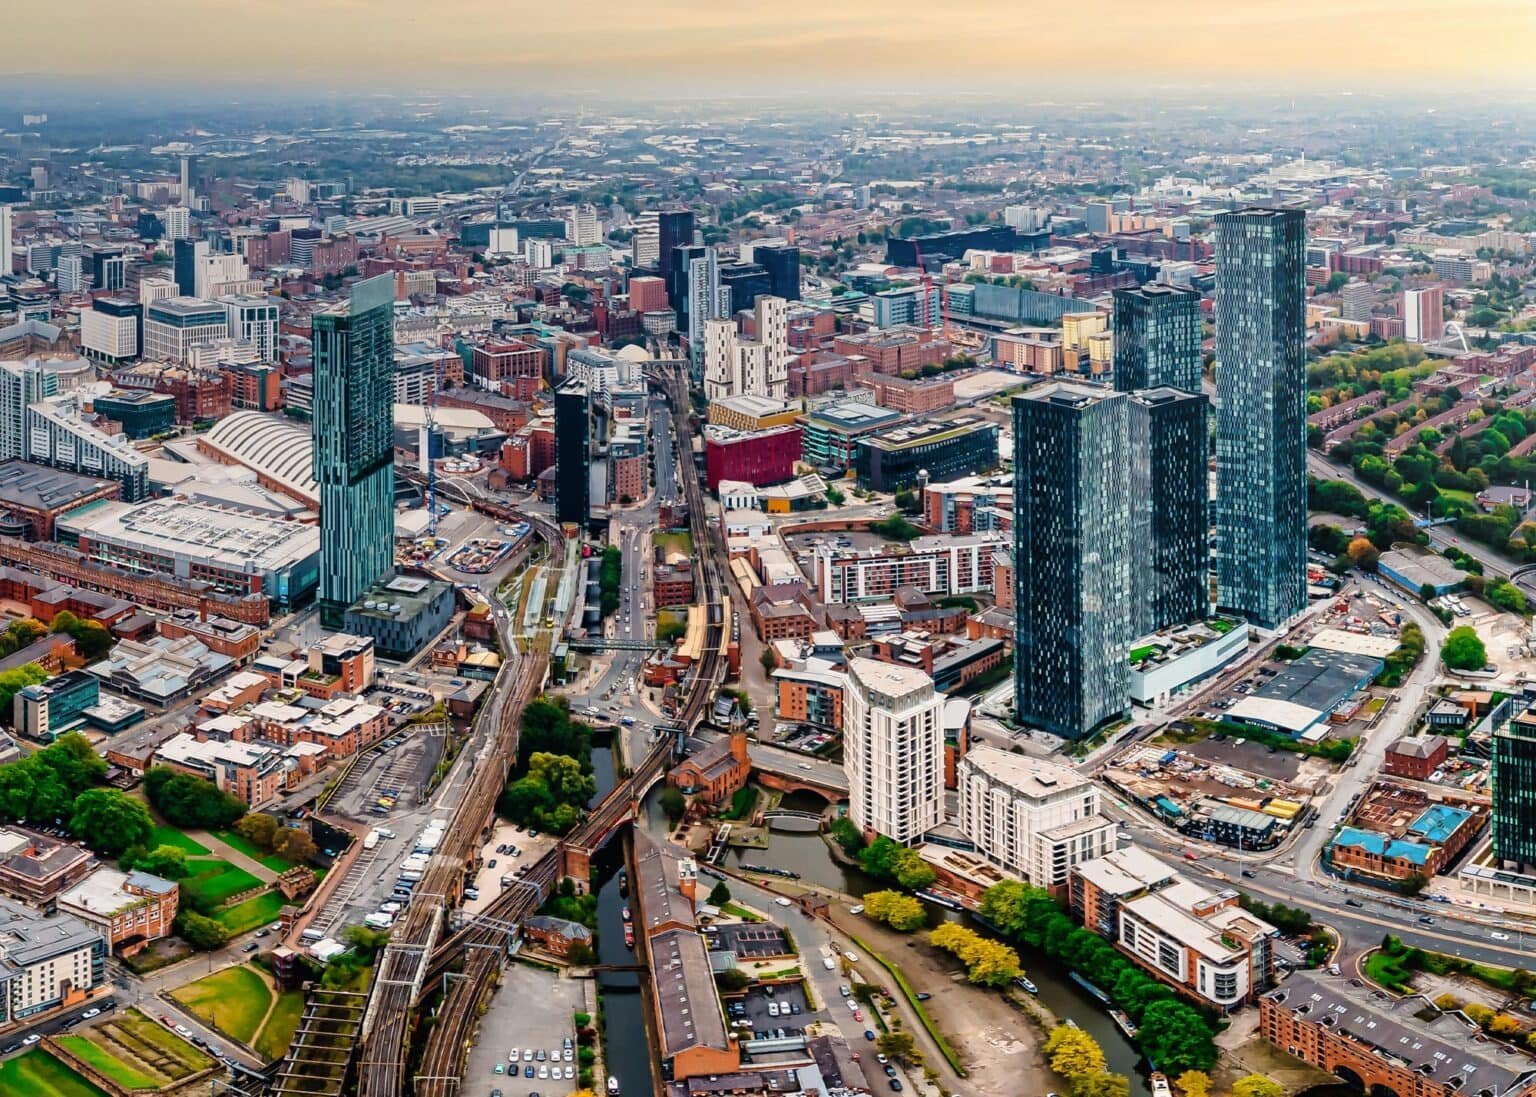
Property Investment Manchester is an attractive option for first-time investors looking to enter the UK property market. With a diverse economy, established universities, strong transport links and ongoing regeneration, Manchester offers opportunities for those interested in building a property portfolio. However, successful investing involves more than finding a property at an appealing price. Understanding local demand, setting a realistic budget and choosing the right investment strategy are essential steps towards making an informed decision.
1. Understand Why Manchester Attracts Investors
Manchester has grown into one of the UK’s leading regional cities, with employment opportunities across technology, finance, healthcare, education, media and professional services. Its diverse economy attracts graduates, professionals, families and businesses, supporting demand for different types of housing.
The city also benefits from a substantial student population and a growing professional workforce. This creates opportunities for landlords considering conventional buy-to-let properties, student accommodation or homes suitable for young professionals.
For first-time investors, Manchester’s appeal lies in the variety of opportunities available. Nevertheless, no property market guarantees capital growth or consistent rental income. Researching individual neighbourhoods and comparing properties carefully can help investors avoid relying on general market trends when making financial decisions.
2. Set a Realistic Investment Budget
Before viewing properties, establish how much you can comfortably afford to invest. Your budget should include the purchase price as well as the additional costs associated with buying, preparing and managing a rental property.
Potential expenses include Stamp Duty Land Tax, solicitor’s fees, survey costs, mortgage arrangement fees, insurance and initial repairs. Depending on the property, you may also need to budget for furnishing, safety improvements or refurbishment work.
It is equally important to retain an emergency fund. Unexpected maintenance, temporary vacancies or changes in mortgage payments can affect your cash flow, particularly during the early stages of property ownership.
If you plan to use a buy-to-let mortgage, compare deposit requirements, interest rates, fees and lending criteria with several suitable lenders. Mortgage affordability and rental stress-testing requirements can influence how much you are able to borrow.
A realistic budget should account for all these factors rather than focusing solely on the deposit. This approach can help you choose an investment that remains financially manageable if circumstances change.
3. Choose the Right Manchester Location
Location plays a major role in determining a property’s rental appeal, purchase price and potential long-term performance. Manchester contains a range of neighbourhoods, each with different characteristics and tenant profiles.
The city centre may appeal to professionals seeking apartments close to offices, restaurants, shopping facilities and transport connections. Salford, particularly areas with convenient access to central Manchester, offers another option for investors researching apartments and residential developments.
Other locations, including Didsbury, Chorlton and parts of Ancoats, may appeal to different groups of renters depending on their budgets, lifestyles and commuting needs. Areas around universities can also attract student tenants, although demand varies by property type and proximity to campus.
Do not choose an area simply because it is frequently mentioned in investment discussions. Investigate recent sale prices, achievable rents, local amenities, transport links and competing rental properties. Visiting neighbourhoods in person can also reveal practical considerations that online listings may not show.
4. Decide on Your Investment Strategy
First-time investors should identify their main objectives before selecting a property. Two common priorities are generating rental income and achieving long-term capital growth, although some investors aim to balance both.
A traditional buy-to-let property involves purchasing a home and renting it to tenants, usually under a residential tenancy arrangement. This approach may suit investors seeking relatively straightforward, long-term ownership.
Student accommodation can provide access to a substantial tenant market, particularly near universities. However, landlords must consider tenancy turnover, maintenance, management requirements and potential vacancies during academic breaks.
House shares may offer opportunities to generate income from multiple tenants, but they can involve additional management responsibilities and regulatory considerations. Licensing requirements may apply depending on the property, occupancy and local rules.
Choose a strategy that reflects your budget, available time and appetite for risk. A property offering a high advertised yield may not be the best option if it requires expensive maintenance or attracts frequent vacancies.
5. Calculate Rental Yield and Cash Flow
Understanding the numbers is essential before committing to a purchase. Rental yield provides a useful starting point when comparing investment properties.
Gross rental yield is calculated by dividing the annual rental income by the property’s purchase price and multiplying the result by 100.
For example, suppose you purchase a Manchester property for £200,000 and receive £1,000 per month in rent. Your annual rental income would be £12,000, producing a gross rental yield of 6%.
However, this figure does not represent your actual profit. You must deduct relevant expenses, including mortgage interest, letting agent fees, insurance, maintenance, service charges and periods without tenants.
Net yield provides a more useful indication of performance because it considers operating expenses. Investors using mortgages should also prepare a cash-flow forecast that accounts for borrowing costs and other regular payments.
Test different scenarios before purchasing. Consider what would happen if interest rates increased, rent fell below expectations or the property remained vacant for several weeks. Conservative calculations can help you understand whether the investment remains viable under less favourable conditions.
6. Understand the Legal Responsibilities
Becoming a landlord involves legal responsibilities that first-time investors should understand before letting a property. Requirements can cover gas safety, electrical safety, smoke and carbon monoxide alarms, energy efficiency and the protection of tenants’ deposits.
You should also understand the tenancy rules in force at the time of letting, including requirements relating to tenant information, property standards and lawful possession procedures. These rules can change, so seek current guidance before entering into a tenancy agreement.
Additional licensing may apply to certain houses in multiple occupation or properties within designated local licensing schemes. Check the relevant requirements with Manchester City Council or Salford City Council, depending on the property’s location.
If you appoint a letting agent, clarify the services included in its fees and how maintenance, inspections, rent collection and tenant communication will be handled.
Taking professional legal and tax advice can help you understand your obligations and avoid costly mistakes.
7. Research Regeneration and Future Demand
Manchester’s regeneration continues to shape its residential landscape, with development bringing new homes, workplaces, amenities and improvements to selected areas. Such changes may increase the attractiveness of particular neighbourhoods, although the benefits are not guaranteed.
When researching an area, distinguish between completed developments and projects that remain proposed or under construction. Examine whether new employment opportunities, transport improvements and amenities are likely to support sustainable housing demand.
It is also worth considering the supply of new apartments. An area experiencing substantial construction may offer modern housing, but a large volume of similar rental properties could increase competition between landlords.
Look for locations with practical advantages and evidence of tenant demand rather than relying entirely on predictions about future price increases.
8. Build a Long-Term Investment Plan
Property investment generally requires patience, careful management and a willingness to adapt to changing market conditions. First-time investors should avoid committing all their available funds to a single purchase without considering future expenses or financial commitments.
Keep records of rental income, repairs, insurance, mortgage costs and other expenditure. Review your property’s performance regularly and compare actual results with your original forecasts.
If managing tenants and maintenance yourself is impractical, a reputable letting agent may help reduce the day-to-day workload, although its fees will affect profitability.
Ultimately, Manchester offers a range of opportunities for new investors, but the right choice depends on individual circumstances. By researching locations, calculating realistic returns, understanding landlord responsibilities and maintaining a financial reserve, you can approach the market with greater confidence.
A well-informed investment decision should be based on reliable figures, careful due diligence and a clear long-term strategy, rather than the expectation that property prices or rental income will always rise.


Leave a Reply